Metaplanet Sold Bitcoin, Bought More Back, and Changed the Playbook
Metaplanet Sold Bitcoin, Bought More Back, and Changed the Playbook
Daily Setup / Perspective
Metaplanet just gave the Bitcoin treasury market something more interesting than another accumulation headline.
It sold enough Bitcoin in Q3 to cover outstanding bond and borrowing principal, held the cash, then repurchased more Bitcoin than it sold.
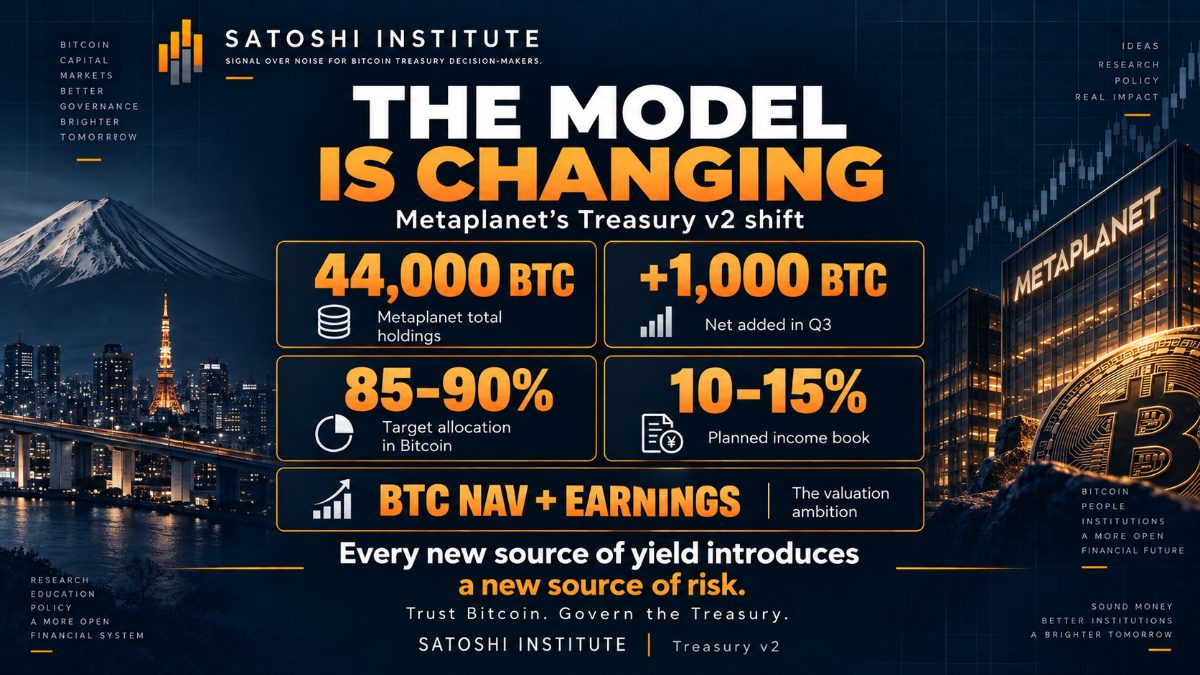
The net result: +1,000 BTC and total holdings of 44,000 BTC as of September 30.
That moves Metaplanet ahead of Twenty One Capital’s roughly 43,514 BTC and, by the figures circulating today, into the number-two position among non-mining public Bitcoin treasury companies behind Strategy.
But the ranking is not the real story.
Metaplanet is also proposing something much more ambitious: a Net Interest Income Strategy designed to turn its balance sheet into an income-producing capital machine.
That is where Treasury v2 gets interesting. The company is no longer describing itself merely as an accumulator. It is starting to look like a financial institution built around Bitcoin.
The Day’s Signals
1. Metaplanet reaches 44,000 BTC by selling first
The headline numbers are straightforward: 44,000 BTC total holdings. +1,000 BTC net during Q3. Approximately $86–87 million of incremental Bitcoin exposure.
And a new ranking above Twenty One Capital’s approximately: 43,514 BTC.
But how Metaplanet got there matters more.
The company reportedly sold Bitcoin sufficient to cover outstanding bond and borrowing principal, held the proceeds in cash, and subsequently repurchased more Bitcoin than it sold.
That is a useful response to one of the persistent criticisms of corporate Bitcoin treasuries:
Can the asset actually function as liquidity when the company needs it?
Metaplanet’s answer was not theoretical.
It converted Bitcoin to cash, addressed liabilities, and then rebuilt the position.
2. Metaplanet wants an income statement around the Bitcoin balance sheet
The larger strategic shift is the proposed Net Interest Income Strategy.
The model appears to be:
- raise relatively inexpensive capital,
- invest primarily in preferred securities issued by other Bitcoin treasury companies,
- and earn the spread.
- Funding sources being discussed include:
- perpetual preferreds,
- unsecured “BitBonds,”
- Bitcoin-collateralized borrowing,
- low-cost yen financing,
- and potentially U.S. capital markets.
The intended asset allocation reportedly keeps approximately 85–90% of assets in Bitcoin and roughly 10–15% in the income-generating book.
That is a very different company from a passive Bitcoin wrapper.
3. The leverage boundary just became more complicated
Metaplanet has previously discussed keeping Bitcoin-related borrowing below roughly: 10% of BTC NAV. But the new income strategy reportedly sits outside that existing guideline.
That detail deserves attention.
Because once a treasury company starts borrowing to purchase preferred securities issued by other treasury companies, the exposure becomes recursive.
Bitcoin treasury company A raises preferred capital.
Bitcoin treasury company B buys the preferred.
Company B may itself finance that purchase with debt or preferred issuance.
Everyone ultimately depends, in varying degrees, on:
- Bitcoin prices,
- capital-market liquidity,
- and investor willingness to fund the structure.
4. The preferred-equity model is becoming the sector’s next experiment
The broader market conversation is shifting away from simple common-stock ATMs.
Preferred equity is increasingly being presented as the next financing engine.
Strategy has STRC.
Strive has SATA.
Smarter Web has launched MORE in the UK.
Metaplanet is exploring its own preferred and bond architecture.
The appeal is obvious.
If preferred securities can be sold near par at an acceptable cost, companies may acquire additional Bitcoin without issuing as much common equity.
That may protect the denominator.
But preferred capital does not eliminate dilution risk.
- It exchanges some dilution risk for:
- dividend obligations,
- seniority,
- refinancing considerations,
- and fixed claims against future capital.
Governance signal
Preferred capital is not free Bitcoin.
Treasury v2 asks: What is the all-in cost?
Not merely the coupon.
The cost includes:
- dividend commitments,
- issuance expense,
- liquidity support,
- call provisions,
- seniority,
- and what happens to the common shareholder during stress.
5. Strategy is increasingly being valued as a financing machine
Citi reportedly raised its Strategy price target from: $136 to $240 while maintaining a Buy rating.
The analytical framework is notable.
The upside was reportedly divided between roughly 34% from Bitcoin appreciation and 16% from mNAV expansion.
Citi also increased its Bitcoin Yield Multiple from: 2.5x to 4.0x with an implied mNAV around 1.24x.
Whatever one thinks about the specific target, the methodology reflects an important transition.
Analysts are no longer valuing Strategy simply as: Bitcoin held × Bitcoin price.
They are assigning value to the company’s ability to use its capital structure to create incremental Bitcoin exposure.
What This Actually Means
The Bitcoin treasury market may be moving into its third phase.
Phase 1: Buy Bitcoin.
Phase 2: Build securities that finance more Bitcoin.
Phase 3: Build financial businesses around the Bitcoin balance sheet.
Metaplanet’s latest strategy is the clearest example. It is no longer proposing merely to hold Bitcoin and wait for appreciation. It wants to raise capital, invest in other treasury securities, earn spreads, preserve a dominant Bitcoin allocation, and eventually be valued on: BTC NAV + earnings.
That is a profound shift. It also creates a much harder governance problem.
The company must now govern not only:
- Bitcoin price,
- custody,
- capital issuance,
- and dilution,
- but also:
- credit risk,
- counterparty exposure,
- interest expense,
- yield spreads,
- preferred-security valuation,
- liquidity mismatches,
- and potentially cross-border financing.
That does not make the strategy wrong. It means the company is becoming more complex. And complexity should never be mistaken for diversification.