Bitcoin Is Trustless. The Corporation Is Not.
Bitcoin Is Trustless. The Corporation Is Not.
Daily Setup / Perspective
Bitcoin removes the need to trust a monetary intermediary.
A Bitcoin treasury company does not.
The moment Bitcoin enters a public corporation, investors inherit management, compensation plans, related-party transactions, warrants, voting control, dilution, financing fees and disclosure quality.
That distinction is becoming impossible to ignore.
The strongest discussion around Bitcoin treasury companies this weekend was not about another acquisition. It was about Metaplanet’s governance, shareholder complaints over dilution and executive incentives, and the company’s subsequent decision to surrender or reduce a substantial portion of executive equity rights.
One reported figure stands out:
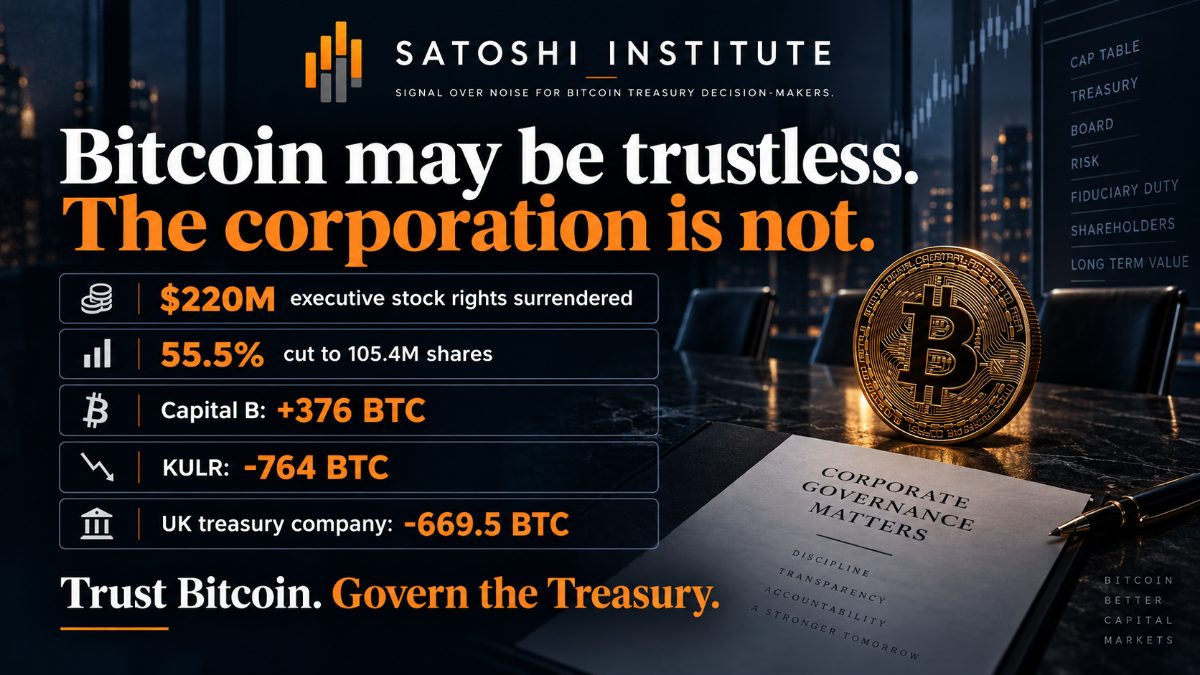
approximately $220 million of stock rights relinquished by management.
Another:
Series 10 warrant exposure reportedly reduced 55.5%, to roughly 105.4 million shares.
Whatever one concludes about the specific allegations circulating on X, the broader signal is unmistakable.
Bitcoin can be trust-minimized. Corporate governance cannot.
The Day’s Signals
1. Metaplanet is learning that “shareholder approved” does not end the governance discussion
A detailed investigative thread circulating on X has raised questions about Metaplanet’s historic capital raises, warrants, related-party relationships, executive incentives and voting concentration.
Some of the claims remain allegations and interpretations rather than independently established facts. But the governance question they raise is legitimate:
How meaningful is shareholder approval when ownership or voting influence is highly concentrated?
Formal approval is important. It is not the same as demonstrating:
- independence,
- arm’s-length dealing,
- economic fairness,
- transparent conflicts management,
- or alignment with minority shareholders.
That distinction becomes especially important when large equity awards or potentially dilutive securities are involved.
Governance signal
A board should not rely solely on:
“Shareholders approved it.”
The stronger question is:
Would an independent director, auditor or institutional investor conclude that the transaction was fair, well-disclosed and appropriately governed?
Treasury v2 requires both authorization and defensibility.
2. Management reportedly gives up roughly $220 million in stock rights
Following the growing shareholder backlash, Metaplanet reportedly announced that its executive chair would surrender stock rights valued at approximately: $220 million.
Reporting also indicates the remaining Series 10 warrant pool was reduced by: 55.5%. to approximately: 105.4 million shares.
Those are not cosmetic numbers.
They suggest that shareholder pressure reached the point where management concluded that the incentive architecture itself had become a credibility problem. That matters because executive incentives are not separate from treasury strategy.
They influence:
- share count,
- dilution,
- control,
- per-share Bitcoin exposure,
- and ultimately the economics received by outside shareholders.
Governance signal
A Bitcoin treasury can accumulate BTC while simultaneously transferring economic value through equity incentives.
That is why gross treasury growth cannot be the only performance measure.
BTC owned by the company is not the same as BTC economically attributable to each shareholder.
3. The dilution trap is moving from theory to the center of the conversation
Capital B reportedly acquired another: 376 BTC for approximately: $29 million bringing holdings to roughly: 3,521 BTC.
That sounds straightforwardly bullish. But some analysis around the transaction points out that diluted BTC-per-share economics moved far less dramatically than gross holdings.
That is the central denominator problem. A company can report:
+10% BTC holdings
while issuing enough new claims that existing owners see little improvement in their economic exposure.
The treasury grows.
The shareholder may not.
Governance signal
Every acquisition announcement should eventually be accompanied by at least two numbers:
BTC added
and
change in fully diluted BTC per share.
Without the second number, investors are being shown the numerator without the denominator.
What This Actually Means
The Bitcoin treasury sector is entering a more demanding phase.
The early question was: Who owns the most Bitcoin?
Then: Who can raise the most capital to buy more?
Now the market is beginning to ask: Who actually owns the economic benefit created by that Bitcoin?
That is a much more difficult question. Because between the Bitcoin and the common shareholder sit:
- warrants,
- preferred securities,
- convertibles,
- executive compensation,
- related-party transactions,
- voting control,
- fees,
- debt,
- and repeated equity issuance.
That entire structure determines how much of the Bitcoin economics ultimately reaches the shareholder.
This is where the phrase “trustless asset” can become dangerously misleading. Bitcoin may be trustless. The corporation is an agency system, and agency systems require governance.